
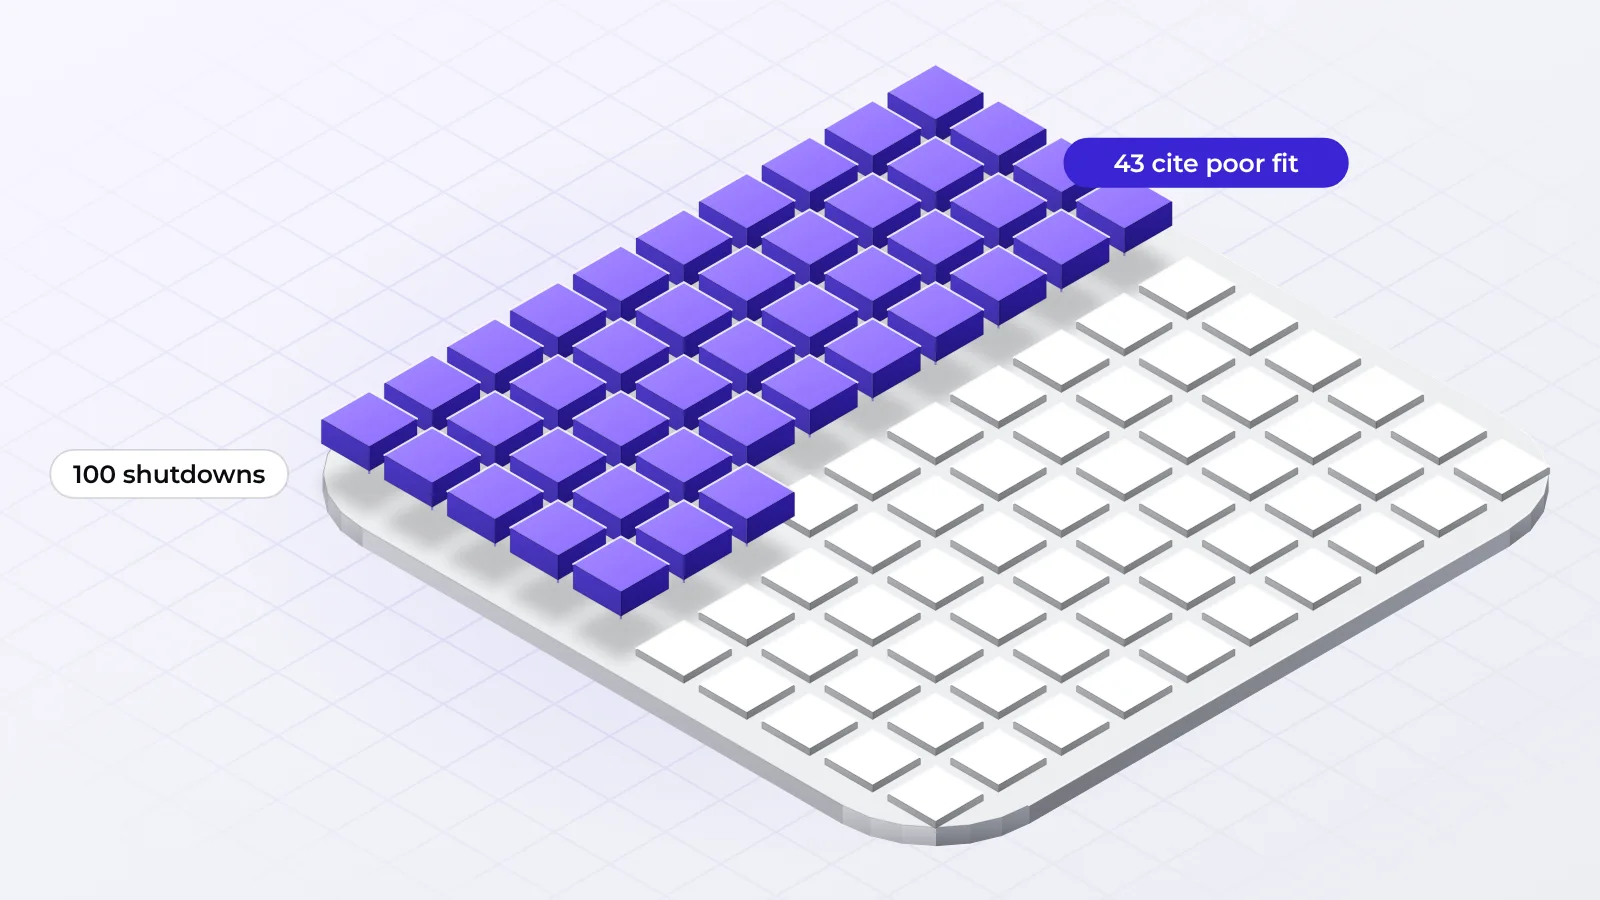
The 43% is the share of failed venture-backed startups, in one CB Insights dataset, that cited poor product-market fit as a reason for shutting down. The base is 385 companies that closed since 2023 and had identifiable reasons, and many cited more than one cause. It isn't your chance of failing for that reason, and it isn't a startup failure rate.
Running out of capital came top, at 70%. CB Insights puts it like this:
“Ran out of capital” tops the list at 70%, but it's almost always the final cause of death, not the root problem.
Cash is how most of these companies died. Weak fit and the other causes are often why the cash stopped coming.
There's no single startup failure rate, because it depends on what you count as failing and which businesses you include. This guide covers where the famous 90% of startups fail comes from, what the CB Insights data shows, how the odds change from idea to seed to Series A, and what you can test cheaply at each stage. I re-checked every figure against its original source on 20 October 2026 and left out the ones I couldn't confirm.
Do 90% of Startups Fail?
Not on any single measure I found. 90% of startups fail is repeated everywhere and sourced almost nowhere. The real answer depends on two choices: which businesses you count, and what you mean by failure.
All new businesses: about a third survive ten years in the US
The broadest data comes from governments, and it covers every kind of business, from cafés to consultancies. In January 2024 the US Bureau of Labor Statistics reported that 34.7% of private-sector business establishments born in March 2013 were still operating in March 2023. The biggest drop came in the first year.
| After 1 year (2014) | 79.6% |
|---|---|
| After 5 years (2018) | 50.6% |
| After 10 years (2023) | 34.7% |
Source: US Bureau of Labor Statistics, The Economics Daily, January 2024. All private-sector establishments, not only start-ups. US data. Chart by ThriveFinity.
The UK picture has a similar shape. The Office for National Statistics' Business demography, UK bulletin (November 2025) tracked businesses born in 2019. By 2024, five-year survival ranged from 43.5% in the South West, the highest region, to 30.6% in the West Midlands, the lowest.
These figures describe a very different population from a venture-backed software company. A new restaurant and a seed-funded B2B platform carry different risks, so it's worth looking at start-ups specifically.
Venture-backed start-ups: it depends on the definition
The most useful framing I know comes from Shikhar Ghosh, then a senior lecturer at Harvard Business School who had held top executive positions at some eight technology start-ups. In a 2011 interview with HBS Working Knowledge, he gave three answers, one for each definition of failure.
| Liquidated, investors lose most or all of their money | 30 to 40% |
|---|---|
| Fails to deliver the projected return on investment | 70 to 80% |
| Falls short of its own initial projections | 90 to 95% |
Source: Shikhar Ghosh, interviewed by HBS Working Knowledge, March 2011. Bars show the midpoint of each published range. The ranges date from 2011. Chart by ThriveFinity.
So if someone tells you 90% of startups fail, the generous reading is that about nine in ten fall short of what their founders first projected. That's a statement about optimism as much as failure. Ghosh put it this way, and added that failure is the norm.
Very few companies achieve their initial projections.
For a founder, two other questions matter more than the headline rate. What usually causes the failure, and which of those causes can you test before you've spent the money? That's where the CB Insights data earns its place.
How to Read Any Startup Failure Statistic
Every startup failure statistic answers a narrower question than its headline suggests. Five checks take a minute and stop you being frightened or reassured by the wrong number.
- Who's in the sample? All new businesses, venture-backed companies, or one accelerator's alumni? The BLS figure includes every kind of establishment. The CB Insights figure covers only VC-backed companies that have already shut down. They can't be compared directly.
- What counts as failure? Closing down, failing to raise, or missing projections? Ghosh's three ranges show how far that one choice moves the answer.
- What's the base? The 43% is a share of failed companies, specifically the 385 where reasons could be identified. It says nothing about companies that succeeded with the same problems.
- Can one company count twice? In the CB Insights data, companies could cite several reasons, which is why the percentages add up to more than 100%.
- How old is it, and where is it from? A cohort that raised seed in 2018 faced a very different funding market from one that raised in 2022. A figure without a date and a place is close to useless.
The detailed venture data is US-heavy. Use it for the pattern, and be careful about treating its exact percentages as your local odds.
90% of startups fail falls apart at the first check. Nobody quoting it can tell you who was counted, and I couldn't trace it to a primary source, which is why it isn't in a chart above. There's also survivorship to allow for. The founders you hear from are mostly the ones who made it, so success looks more repeatable than it is. Post-mortem data like CB Insights' is useful precisely because it records the companies that didn't.
What the CB Insights Data Says
CB Insights' March 2026 report is the most detailed public look I know of at why venture-backed startups shut down. It covers 431 companies that closed since 2023. For the 385 where the reasons could be identified, poor product-market fit was the most-cited reason after running out of capital, at 43%.
The report, The top 9 reasons startups fail, drew on public post-mortems, founder interviews and shutdown announcements. CB Insights excluded companies that had a prior exit.
| Ran out of capital | 70% |
|---|---|
| Poor product-market fit | 43% |
| Bad timing or macro conditions | 29% |
| Unsustainable unit economics | 19% |
Source: CB Insights, The top 9 reasons startups fail, March 2026. Base: 385 of 431 VC-backed companies that shut down since 2023, where reasons could be identified. Totals exceed 100%. Chart by ThriveFinity.
Three details in the report are more useful than the headline.
- Money didn't save them. The 431 companies raised a combined $17.5B before closing. The median company raised $11M and the average was $48M, pulled up by a long tail of very well-funded failures.
- Most fit failures were early. Two-thirds of the product-market fit failures were early-stage companies that never found a market. But 20 companies at Series B or later also cited poor fit, having raised on early traction that never widened into a real market.
- Timing hit some sectors hard. Bad timing drove a disproportionate share of failures in climate and energy, food and agriculture, and blockchain, sectors that drew heavy investment in 2021 and 2022.
Timing is the hardest cause to see from inside a company. Bill Gross has founded and incubated many start-ups. In this TED talk he ranks hundreds of companies on five factors to find what set the successes apart.
Two cautions before you lean on the 43%. It's the share of failed companies where fit was a reason, which says nothing about the chance that yours fails for that reason. And these are reasons drawn from post-mortems and announcements. Founders don't always name the uncomfortable cause, so I'd expect fit problems to be under-reported rather than over-reported. That's my reading, and the report doesn't say it.
To use the data in your own planning, turn each of the four main causes into a question you can answer this month. How many months of runway do we have, and what has to be true by the end of them? What's our best evidence that buyers want this at this price, and did any of it involve them paying? Do our buyers have budget now, or are we early? Does each customer make money over its life on cautious numbers? If any answer is we don't know yet, that's your next piece of work, and it's far cheaper to find out now than to read about it in your own post-mortem.
Running Out of Cash Is Usually the Symptom
Running out of capital is how most failed startups die, and poor product-market fit is often why the capital ran out. CB Insights says as much: the more telling causes "reveal why the capital dried up in the first place."
The mechanism is simple. A company without strong fit struggles to show the numbers that justify more money: customers who stay, who pay and who bring others. Investors look at those numbers before the next round. If they're weak or falling, the round doesn't happen, the company spends what it has, and the post-mortem says we ran out of cash. That's true and incomplete.
The fix for each problem is different. If cash is the real issue, a bridge round, cost cuts or a longer runway can solve it. If fit is the issue, all of those only extend the time before the same wall. So before you raise to extend runway, be honest about which problem you're solving. Three questions I'd ask before any bridge round or cost-cutting plan:
- If we had twice the runway, what specific number would we expect to be different at the end of it, and why?
- Is retention for our newest customers better or worse than for our oldest?
- What would a sceptical investor say is the real reason the last round was hard, and do we have evidence that they're wrong?
If the honest answer to the first is we'd have more time to figure it out, the problem is fit, and the runway should be spent testing fit, deliberately and quickly.
I don't want to overstate this. Some companies with real fit do die for lack of cash, especially when the funding market turns, and the 29% citing bad timing is a reminder that luck matters. But for most early-stage companies the first question is whether buyers want what you're selling at a price that works. Cash comes second.
Startup Failure Rate by Stage
The failure rate changes by stage, and so does the cause. The best public data covers the funded stages, from seed to Series B. For the idea stage, before any money is raised, there's no reliable dataset at all, which is worth knowing before you trust anyone's number for it.
Each stage needs its own definition of failure. At seed it usually means not raising the next round in time. At Series A it means not reaching Series B or profitability. A company that hasn't raised again isn't necessarily dead. Some get acquired, some grow on revenue, and some sit for years in between.
| Stage | What the best public data says | Source |
|---|---|---|
| Idea, before any funding | No reliable public dataset. Ideas that are dropped early rarely get recorded anywhere. | None we would rely on |
| Seed to Series A | 30.6% of Q1 2018 seed companies reached Series A within two years, against 15.4% of the Q1 2022 cohort. For 2022 seed companies overall, 24% had reached Series A by November 2025. | Carta (via Konvoy, 2024) and Carta (2025) |
| Series A to Series B | About 28% of 2018 Series A companies reached Series B within two years, against 9% of those that raised their Series A in Q3 2022. | Carta (October 2024) |
| All funded stages, cause of shutdown | 70% ran out of capital, 43% poor product-market fit, 29% bad timing, 19% unit economics. | CB Insights (March 2026), 385 companies |
Why idea-stage failure is invisible in the data
The idea stage is where the most ideas die and the least gets recorded. An idea that's dropped after a month of research never raises money, never registers a company and never writes a post-mortem, so it appears in no dataset. The failure statistics you see are mostly about companies that got far enough to raise money and then failed.
That makes the cheapest failures the ones nobody counts, and I think they're the best kind to have. Ending an idea after ten buyer conversations costs weeks. The CB Insights companies raised a median of $11M before they closed.
The data can't tell you the cause stage by stage with any precision. Earlier failures are the most preventable with evidence, because the questions are about demand and price. Later ones need different skills: hiring, sales design and finance. If you're at the idea stage, the cheapest risk to reduce is also the one most likely to sink you.
The Seed to Series A Cliff
Getting from seed to Series A has become much harder since 2018. Konvoy, a venture firm, reported Carta's figures from its first VC Fund Performance report in its newsletter Failure to Launch: The Series A Crunch.
While 30.6% of companies that raised a seed round in Q1 2018 raised Series A within two years, only 15.4% of startups that raised a seed round in Q1 2022 could do so in the same timeframe, a ~50% decrease overall.
| Raised seed in Q1 2018 | 30.6% |
|---|---|
| Raised seed in Q1 2022 | 15.4% |
Source: Carta VC Fund Performance report, as reported by Konvoy, 2024. Not raising a Series A within two years is not the same as shutting down. Chart by ThriveFinity.
Carta's own posts add three data points.
- The low point. In July 2024, Peter Walker of Carta wrote that only 15% of companies that raised their seed in Q2 2022 made it to Series A in two years, "the lowest such percentage" in the data.
- A kinder long view. In November 2025, Carta reported that 24% of startups that raised seed in 2022 had reached Series A so far. It also noted that "historical norms suggest 50% of seed companies eventually raise a Series A," and that about six in ten companies from 2016 to 2018 did, a figure it said is likely a little inflated by how Carta sampled at the time.
- A tighter next step. In October 2024, Carta's post on the Series A to B leap put it at about 28% of 2018 Series A startups reaching Series B within two years, against 9% of those that raised their Series A in Q3 2022.
For you, this mostly means the bar for the next round has gone up. I'd expect investors to ask for retention curves by cohort, revenue from named customers they can call, and acquisition cost by channel. If any of those would be hard to show today, that's the gap to close before the raise starts, because investors will find it during it.
I'd also be careful reading most seed startups fail from this data, because many of the companies that didn't raise a Series A are still alive. If you've raised a seed round, work backwards. Take your runway, subtract the months a raise takes, and ask what your retention and revenue need to look like by then. That gap is your real plan.
The Warning Signs Before a Shutdown
Startup failure is rarely sudden. In CB Insights' data, most companies showed measurable decline in the year before they closed. The report picked out four patterns from its own signals.
- Health scores fell. Among companies with a full 12 months of Mosaic data (CB Insights' 0 to 1,000 measure of private company health), 72% saw their score decline in the year before death, by 15% on average.
- Partnerships dried up. Among the 206 companies with tracked business relationships, partnership activity fell 44% between the period 12 to 24 months before death and the final 12 months.
- Headcount shrank. Two-thirds of companies with headcount data were shrinking in the six months before they closed. Nearly a third died with 10 or fewer employees, and about 15% with more than 100.
- The money stopped well before the end. The median time from last fundraise to shutdown was 22 months, so over half died within two years of their last raise. Nearly a quarter had been walking dead, in CB Insights' phrase, for more than three years before they officially went under.
CB Insights also counted nearly 50,000 VC-backed startups that hadn't raised funding since the start of 2023. That isn't a count of failing companies, because some are profitable and some simply don't need to raise. It's a reminder that published failure rates only capture companies that have formally closed.
Four signals to watch inside your own company
External data shows up late. These internal signals usually show up first. They're my own checklist, built on the patterns above, and no study backs it.
- Retention getting worse by cohort. Each new group of customers stays a little less than the one before. Strong fit usually shows the opposite as the product improves.
- One channel doing all the work. Most new customers come from one source, often the founder's network. If that channel stops, so does growth.
- Friction at renewal. Customers don't cancel, but they hesitate. Procurement asks for justification and your champion goes quiet.
- Acquisition cost creeping up. It costs more each month to win a customer, with no matching rise in what they're worth.
Any one of these can have an innocent explanation. Three or four together, over a couple of quarters, deserve a hard conversation before the next fundraise rather than after it.
What the Numbers Don't Tell You About Your Odds
Base rates describe groups, and your company is one case. The failure data is a starting point, and the evidence you gather should move you a long way from it in either direction. Paying customers who renew, a channel that gets cheaper as you scale and a market with real budget all push your odds up. A demo that everyone praises and nobody buys pushes them down.
That's why I don't think the data should put anyone off building. It should change the order you do things in. CB Insights found that weak fit was the most-cited cause after cash and that two-thirds of those fit failures happened early, so the highest-value work at the start is the work that tests fit: buyer conversations, commitments, pricing tests and honest numbers.
Three things the statistics can't capture:
- A shutdown records the company. It doesn't record what the founders learned or did next.
- Not raising isn't failing. Some of the companies that never raised a Series A are profitable businesses that didn't need one.
- Timing is partly luck. You can test whether buyers have budget now, but you can't control what the economy does next year.
The Four PMF Failure Archetypes
Poor product-market fit covers several quite different failures, and each needs a different fix. We sort them into four archetypes. It's our own framework, and its job is to help you work out which kind of fit problem you might have before you decide what to do about it. A distribution problem won't be solved by rebuilding the product, and an imagined market won't be solved by better marketing.
| Archetype | What it is | Warning sign | Question to ask |
|---|---|---|---|
| The Imagined Market | The problem is real but it's an irritation, not a pain anyone budgets for. Buyers agree it's annoying and won't pay to fix it. | Lots of interest in demos, few trials turning into payment, usage that fades once anything is free. | Have any buyers offered to pay, or pre-pay, without being pushed? What do they spend on the problem today, in time or money? |
| The Demand Mirage | Demand for the category is real, but not for your version. An incumbent is entrenched, the buying process doesn't fit how you sell, or your difference doesn't matter to the person who signs. | Healthy inbound and evaluations that end with the buyer staying with what they have or building it themselves. | Who holds the budget for this today, what are they paying, and has anyone switched to you from it? |
| The Distribution Phantom | Right product, right buyers, no affordable way to reach them at scale. Users who find it like it. Growth stalls once the founder's network is used up. | Strong retention in a small group, almost all of it founder-sold, and no channel that works when you put more money in. | What does a customer cost to acquire through each channel on its own, and what happens to that cost when you spend more? |
| The Unit Economics Trap | Customers love it but the business loses money at scale. Margins shrink with volume, or the price needed for profit is more than the market will pay. | Good retention and referrals, but each new cohort contributes less than the last, so growth makes losses bigger. | What happens to gross margin and payback at three times your current volume, on cautious assumptions? |
The Imagined Market
This is the one I'd check first at the idea stage. The tell is a gap between enthusiasm and payment, and it can take years to notice. Garry Tan of Y Combinator described one way founders miss it:
It’s surprisingly common to spend all your time fighting the other players in your market and then realizing years later the market didn’t really exist.
If this sounds like you, stop building features and start asking for money. A paid pilot, a deposit or a signed letter of intent will tell you more in a fortnight than another round of demos. It's also the archetype most exposed to polite feedback. Friends, advisers and, these days, AI assistants all lean towards agreeing that a problem is real, and I've written about why ChatGPT tends to call your idea brilliant.
The Demand Mirage
This one looks like success for longer, because budgets exist and buyers take your calls. Study the deals you lost as closely as the ones you won, and ask the buyers who chose the incumbent what would have made them switch. The answer often points to a narrower segment where your difference matters a lot. Our guide to B2B positioning covers how to find it.
The Distribution Phantom
CB Insights' 20 Series B or later companies that still failed on fit are a reminder that early traction doesn't always widen into a market. Test channels one at a time with a fixed budget and a target cost per customer, and keep the ones that hold their cost as you spend more. If none do, the options are a buyer you can reach more cheaply, a higher price that pays for the channel, or a smaller business than you planned.
The Unit Economics Trap
This overlaps with the 19% of failures CB Insights put down to unsustainable unit economics. Rebuild your model from the cohort level up, including support and discounts, and test a higher price on new customers before you scale. Growing a business that loses money on each customer only makes the loss arrive sooner.
For what real fit looks like next to what founders often mistake for it, Michael Seibel's short talk is still one of the clearest. He was a partner at Y Combinator when he recorded it in 2018, and he co-founded Justin.tv and Socialcam:
What to Test at Your Stage
The risk you carry depends on where you are, so the test should too. Here's how I'd prioritise, stage by stage, with the cheapest useful test first.
Before you build: test demand
At the idea stage your biggest risk is the Imagined Market or the Demand Mirage, and both are cheap to test compared with building first.
- Talk to at least 10 potential buyers about their current process, what it costs and what they've tried. Don't pitch.
- Look for commitments rather than compliments: a letter of intent, a paid pilot, a pre-order, or time they give you for a real trial.
- Model your numbers on pessimistic assumptions, and write down before you start the result that would make you stop.
Our startup idea validation framework lays out the steps, including how to run those buyer conversations, and the guide to what market validation is explains what counts as evidence.
After launch, before Series A: test retention and channels
Once you have customers, the risk moves to the Distribution Phantom and early signs of the Unit Economics Trap. These are the problems behind much of the seed to Series A drop-off.
- Track retention by cohort. A single blended number hides the trend.
- Work out acquisition cost by channel, separately. A good blended figure can hide one channel doing all the work.
- Test what happens when you put more money into your best channel. If the cost per customer jumps, you've found your ceiling.
- Check gross margin at higher volume on cautious assumptions.
When you're about to raise: test your claims
Investors will check your numbers, and gaps they find themselves cost more trust than gaps you've flagged. Our guide to how investors verify startup claims shows what they look at first, and the Series A claim checklist is a free way to run the same checks on your own deck.
- Source every market-size figure to the original report, and be ready to explain how it was calculated.
- Make sure every customer number in the deck matches what's in your data room.
- Show retention by cohort, with the weak cohorts included and explained.
- Remove any claim you couldn't defend in a follow-up email with a link.
One point applies at every stage. Be wary of anything that makes you feel validated without giving you evidence. A good meeting, an encouraging adviser and an enthusiastic chatbot all feel like progress. Only buyer behaviour counts, which is why I'd stop weak ideas early.
Where ThriveFinity Fits
We help at the points where an honest, evidence-graded answer is worth paying for. Each paid service ends in a verdict a named person signs, and that verdict is allowed to be Stop.
- Before you build or launch. Offer Validation tests an idea or offer. The free Offer Signal gives a structured, unsigned read in under an hour. The Build Verdict (£149) runs 12 evidence lenses graded A to E and is signed within 24 hours. Its verdict is Go, Go With Conditions, Change Course, Stop or Wait.
- When you have one big go-to-market call. The Decision Brief (£749, 48-hour target) takes one decision, such as which segment to lead with or how to price, to a signed recommendation with a 90-day plan.
We don't yet publish how often each verdict is given. Our verdicts and grades page explains why: we'll publish once the sample is large enough to mean something.
We're not the right fit for every stage.
- If you're past Series A and your problem is building a sales team or a repeatable motion, you need operators and sales leadership more than a validation verdict.
- If your big question is technical, such as whether something can be built at all, answer that with a prototype first.
- If you just want encouragement to start, a mentor or an accelerator will do that better.
Whatever you choose, test the cheapest thing that could prove you wrong, and do it before you spend the money. The 43% doesn't say you'll fail. It says one of the most common ways to fail is one you can often check in advance.
❓ Common Questions
What is the actual startup failure rate?
Do 90% of startups really fail?
What is the number one cause of startup failure?
What percentage of startups reach Series A?
Can you spot startup failure before it happens?
Sources
- CB Insights. The top 9 reasons startups fail. 5 March 2026 (431 VC-backed shutdowns since 2023, 385 with identifiable reasons). Checked 20 October 2026.
- US Bureau of Labor Statistics. 34.7 percent of business establishments born in 2013 were still operating in 2023. The Economics Daily, 12 January 2024.
- Office for National Statistics. Business demography, UK: 2024. 20 November 2025.
- Carmen Nobel. Why Companies Fail, and How Their Founders Can Bounce Back (interview with Shikhar Ghosh). HBS Working Knowledge, 7 March 2011.
- Konvoy. Failure to Launch: The Series A Crunch (reporting Carta's VC Fund Performance report). 2024.
- Peter Walker, Carta. Seed Graduation Depends Massively on When You Raised. 9 July 2024.
- Peter Walker, Carta. Only 24 Percent of 2022 Seed Startups Have Reached Series A. 5 November 2025.
- Peter Walker, Carta. Making the Series A to B Leap Is Hardest in Six Years. 15 October 2024.
- Garry Tan. Post on X about focusing on competition over customers. 30 March 2023. A view, not evidence.
- ThriveFinity. PMF Failure Archetypes and warning-signal checklist (own framework, no external data). Published scope and prices: /offer-validation (October 2026).